FOR decades, Zimbabwe’s platinum story has been told from beneath the ground — about the riches buried along the Great Dyke and the billions generated from extracting them.
But the country’s next platinum battle is no longer about what lies underground. It is about what happens after the ore leaves the mine.
Inside Zimbabwe’s furnaces, concentrates are transformed into matte.
That matte can then be stripped of base metals, leaving a platinum group metals (PGM)-rich residue before individual metals — platinum, palladium, rhodium — are separated and refined.
And this is where the real contest begins. How much of the value in Zimbabwe’s platinum can the country capture before the metal leaves its borders?
The question has become urgent as the Government enters a new phase of its mineral beneficiation drive. Under the National Development Strategy 2 (NDS2), covering 2026 to 2030, Zimbabwe wants producers to move beyond matte to residue and ultimately isolate individual PGMs.
It raises a harder question: Can Zimbabwe build a competitive refining industry — or will its platinum continue crossing the border in semi-processed form because South Africa remains inexpensive and more established?
That is the real platinum story unfolding now.
That will take solar capacity to 80MW.
The investment is more than environmental. It is an industrial-security strategy. The Chamber of Mines has reported power interruptions affecting operations.
Zimbabwe cannot demand deeper processing while treating energy security as separate.
A refinery needs electricity every day, not only when the grid has surplus.
The feedstock equation
Zimbabwe has three major producers — Zimplats, Unki and Mimosa — with Karo and Great Dyke Investments set to expand output.
And more mines mean more feedstock, which improves the economics of larger plants.
But the equation is simple: Mine output + processing capacity + refinery utilisation = refinery economics.
If production is insufficient, a refinery runs below capacity and unit costs rise. Once costs rise, the South Africa alternative becomes more attractive.
Thus, the beneficiation strategy should be designed around the economics of the entire PGM ecosystem.
The skills Zimbabwe cannot import forever
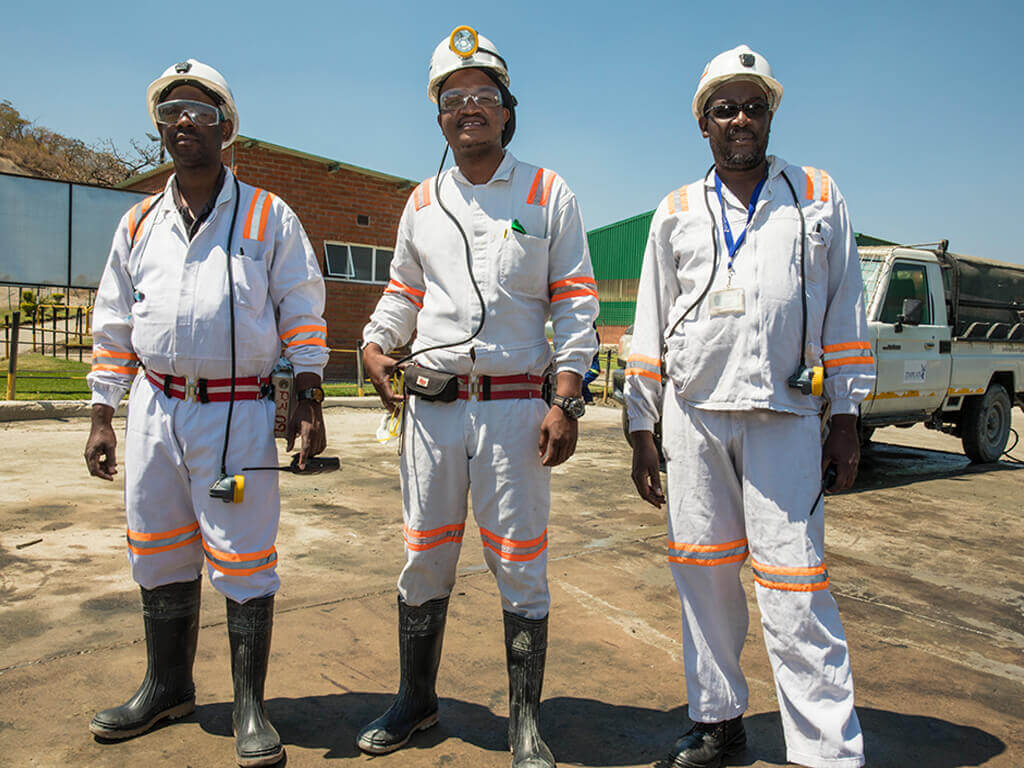
There is another resource beneath the ground—people. Mining needs miners and smelting needs furnace operators and metallurgists.
Mining needs chemical and metallurgical engineers, laboratory scientists, process specialists, environmental experts and technicians.
Can Zimbabwe produce enough specialists for an advanced PGM refining industry?
Can companies transfer enough technology so expatriate expertise becomes Zimbabwean expertise?
Therefore, beneficiation should create more than refined metal. It should create skills, engineering firms, laboratories, suppliers, technology and industrial capability. The ore will run out. But a refinery, a trained metallurgist, and an engineering firm can outlive any mine.-herald
The US$1,5 billion clue
The first evidence of the changing value chain is in Zimbabwe’s export statistics.
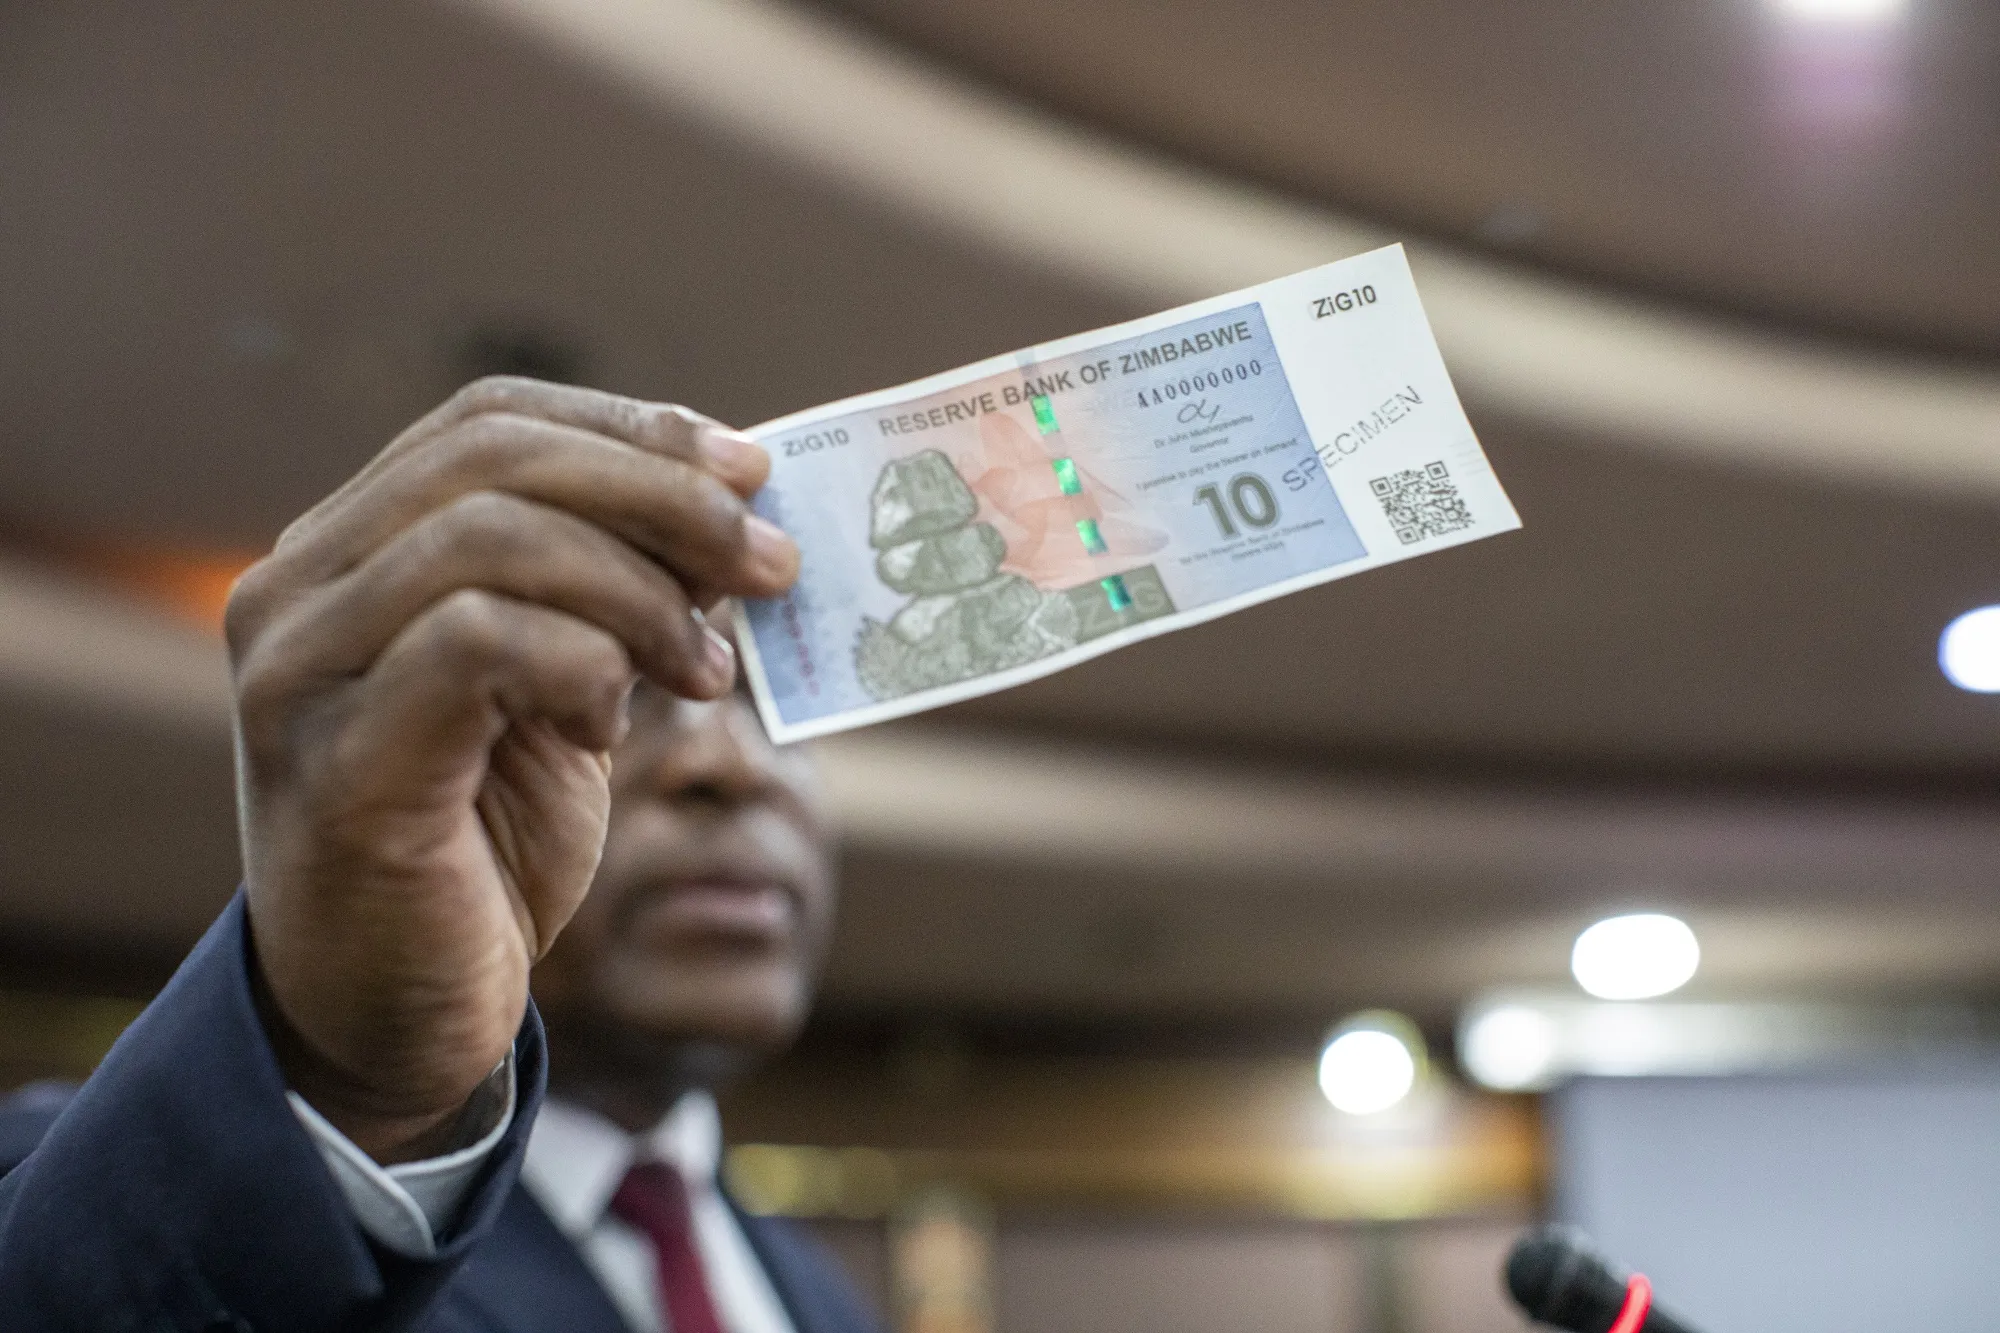
According to the Minerals Marketing Corporation of Zimbabwe (MMCZ), the country exported 37 194 tonnes of PGM matte worth US$1,5 billion in 2025 — up 71 percent from US$914 million in 2024.
Over the same period, PGM concentrate exports fell 52 percent in volume to 73 506 tonnes, while value declined 44 percent to US$306 million.
MMCZ attributed the shift to increased beneficiation of concentrates into matte through toll-processing arrangements.
On the surface, the numbers tell a straightforward story: Zimbabwe is processing more platinum before export.
But the US$1,5 billion figure conceals another reality. Matte is not the end of the value chain; it remains an intermediate product.
Further processing is required to remove base metals and separate PGMs into individual saleable metals. Zimbabwe’s beneficiation journey has moved from “can we stop exporting concentrate?” to the harder question: “can we economically refine what we are already smelting?”
The value chain is a ladder: ore → concentrate → matte → residue → individual refined metals.
Every upward step requires more technology, capital, energy and specialised skills. But every step also creates the possibility of capturing more economic activity inside Zimbabwe.
The country has climbed from concentration to smelting, and now it wants to climb again. The policy is no longer just about stopping raw mineral exports. It is about creating an industrial chain around those minerals.
A refinery is not simply pipes and tanks — it is the centre of an industrial ecosystem.
What the US$1,5 billion does — and does not – mean
It would be tempting to look at US$1,5 billion and conclude that Zimbabwe is already capturing enormous value. That would be misleading. Export value is gross, not income retained domestically.
Mining and processing costs, electricity, transport, finance, equipment, chemicals, taxes and royalties all sit inside the economics.
The buyer of matte still needs to recover and separate individual metals. Some economic activity, and value, therefore, remains outside Zimbabwe.
Simplistic claims that domestic refining will automatically add “billions” should be treated cautiously. The value captured will depend on grades, recovery rates, prices, plant utilisation, energy costs, capital expenditure, financing and technology.
The prize is real, but it has to be calculated.
Zimplats: The industrial test case
If beneficiation ambitions are to become more than policy, look to the Selous Metallurgical Complex. Zimplats is investing US$190 million in refurbishing its base metal refinery (BMR), with US$36 million already spent by December last year.
The BMR will process nickel and base metals, a critical bridge between smelting and precious-metal purification.
Zimplats chief executive officer, Mr Alex Mhembere, has said a precious-metal refinery will be considered after the BMR is commissioned.
“That is what we will look at when the base metal refinery has been commissioned,” he is on record as saying.
Zimbabwe is not building one plant that instantly turns matte into finished platinum.
The chain is being built in stages. The ultimate prize — separating individual precious metals — is more demanding.
It requires hydrometallurgical processes, specialised labs, environmental controls, technical expertise, and crucially, reliable feedstock.
That raises a question not yet answered: How much platinum-bearing material can producers collectively supply, and at what cost?
A billion-dollar plant running at half capacity could become an expensive monument to beneficiation, not a competitive asset.
The South African question
This is where ambition meets commercial reality. South Africa has spent decades building the infrastructure, skills and supply chains to process PGMs.
Zimbabwe is trying to build that ecosystem later. If a mine can send matte to an established South Arican refinery, why spend hundreds of millions building capacity at home?
The answer cannot be patriotism — it has to be economics. A Zimbabwean refinery needs competitive costs, sufficient feedstock, reliable electricity, technology, affordable capital and policy predictability.
That is when beneficiation stops being a motto and becomes an industrial-economics problem. SFA Oxford analyst Mr RJ Coetzee said Zimbabwe is well-positioned to be one of the world’s most important future platinum sources.
“These mines are getting deeper and deeper, and this is where Zimbabwe has a real advantage because your mines are relatively shallower.
“The Great Dyke is less developed, meaning there is opportunity for shallower mining and mechanisation, which is not possible with ageing SA mines,” he said at the recently held Chamber of Mines of Zimbabwe annual conference in Victoria Falls.
South Africa holds over 80 percent of global platinum reserves while Zimbabwe has the second-largest deposits.
According to the World Platinum Investment Council (WPIC), more than 78 percent of global PGM reserves are in Southern Africa, mainly the Bushveld and Great Dyke.
WPIC estimates Zimbabwe hosts about 32 million ounces of PGMs.
Mr Coetzee said Zimbabwe is among the few countries with substantial undeveloped platinum resources to support the industry’s next growth phase.
The electricity test
No refinery operates without power. Smelting and refining are energy-intensive, even as Zimbabwe pursues lithium, steel and ferroalloys.
Zimplats commissioned a 35MW solar plant in August 2024. A further 45MW Phase 2A, costing
US$54 million, is due in H1 2027.